Biometric Synchronization Aligning Portable Wallets with Institutional Channels for Vendor Recurrence Models
Petra Carter · Aug 20, 2026
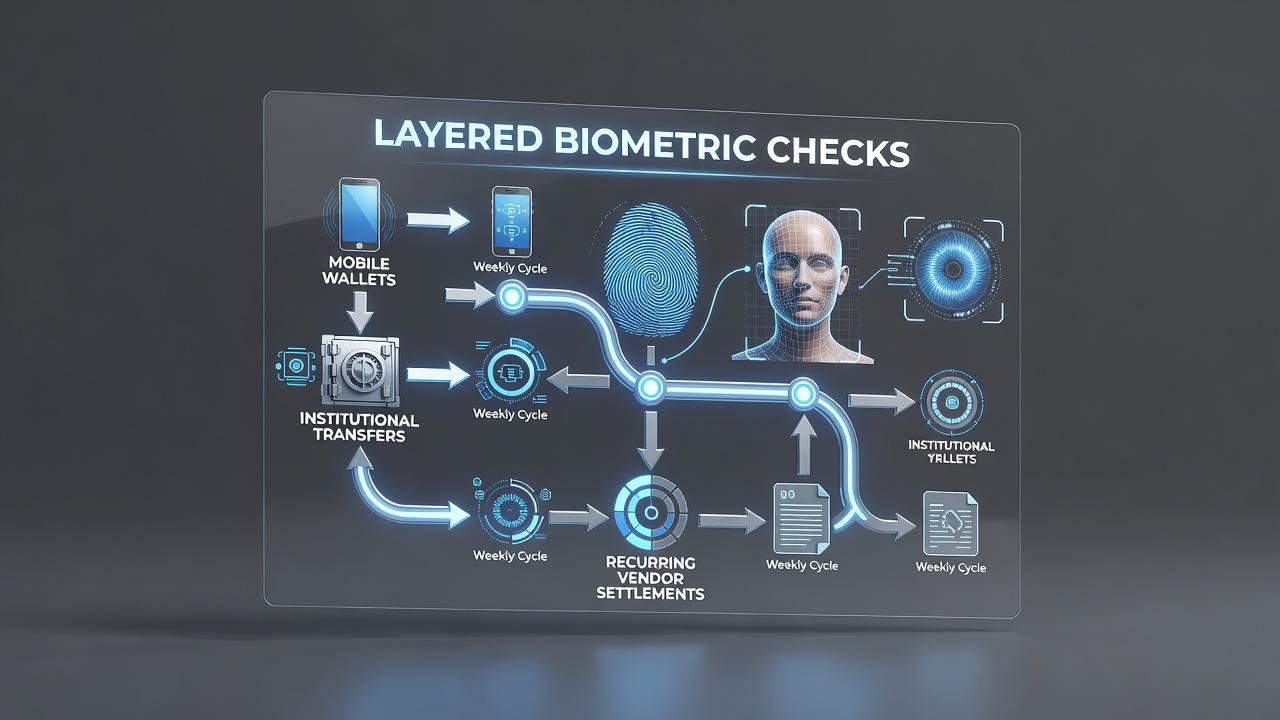
Biometric Synchronization Aligning Portable Wallets with Institutional Channels for Vendor Recurrence Models
Financial networks have expanded biometric verification steps that connect mobile wallets directly to institutional transfer systems, and these layers handle recurring vendor settlements by matching user identity data across multiple points before funds move between accounts. Observers note that such coordination reduces mismatches in payment cycles where vendors receive regular payouts from both consumer-facing apps and larger banking entities, while data from regulatory bodies shows increased adoption rates through 2026.
Core Components of Layered Biometric Integration
Biometric protocols typically combine fingerprint scans, facial recognition, and voice patterns to authenticate transactions, and these elements link mobile wallet applications to institutional channels that process bulk settlements for vendors operating on subscription schedules. Researchers at institutions like the Federal Reserve have documented how these sequences verify identity at wallet initiation, during transfer authorization, and again at settlement confirmation, creating checkpoints that align consumer payments with corporate banking records. Systems process these checks in sequence because each layer cross-references live data against stored templates, and this approach supports recurring models where vendors expect consistent inflows without manual intervention each cycle.
Coordination Between Mobile Wallets and Institutional Transfers
Mobile wallets initiate payments through biometric triggers that send encrypted signals to institutional processors, and those processors then validate the same biometric markers against records held in banking networks before releasing funds into vendor accounts. This linkage proves essential in recurring vendor settlements because it maintains continuity across different jurisdictions and currency types, whereas separate verification paths often create delays. Data indicates that by August 2026 integration frameworks had incorporated real-time matching algorithms that flag discrepancies in biometric readings before they reach settlement stages, and industry reports highlight examples where vendors in cross-border supply chains benefited from fewer rejected transfers as a result.
Application in Recurring Vendor Settlement Cycles
Vendors who rely on subscription-based revenue streams use these coordinated systems to receive payments at fixed intervals, and the biometric layers ensure that each incoming transfer from mobile sources matches institutional records without requiring additional manual approvals. European Central Bank analyses reveal that such setups handle high volumes by routing verifications through shared APIs that connect wallet providers to bank settlement engines, and this reduces processing times while preserving audit trails for compliance purposes. One case study from a regional payment network demonstrated how layered checks prevented duplicate entries in vendor ledgers during multi-currency operations, since each biometric confirmation updated a central matching database accessible to both mobile and institutional sides.
Technical Sequences Supporting Reliability
Authorization begins when a user activates a wallet transaction via biometric input, after which the system forwards the verified token to institutional gateways that perform secondary checks against account histories and settlement rules. These sequences incorporate fallback options like secondary device confirmation when primary biometrics encounter environmental interference, and observers have tracked how such flexibility maintains settlement accuracy across recurring vendor schedules. Academic studies on payment interoperability further show that combining these layers with timestamped data logs allows reconciliation teams to trace every step from wallet initiation through to final institutional credit, and this traceability supports vendors who manage payments across multiple client platforms simultaneously.
Future Developments in Verification Alignment
Developments scheduled for later periods include expanded use of behavioral biometrics that analyze transaction patterns alongside physical traits, and these additions aim to strengthen coordination between mobile wallets and institutional channels without increasing user friction during recurring settlements. Regulatory updates from bodies in various regions continue to emphasize standardized data formats that facilitate smoother handoffs between systems, while pilot programs test enhanced encryption methods to protect biometric templates throughout the transfer process. Those who monitor these trends note steady growth in vendor adoption as the technology matures and integrates with existing settlement infrastructures.
Conclusion
Layered biometric checks provide structured pathways that connect mobile wallets to institutional transfers, and they support recurring vendor settlements by enforcing consistent identity verification at each stage of the payment flow. Evidence from established financial authorities confirms measurable improvements in processing reliability, and ongoing refinements continue to address challenges in multi-jurisdictional environments. These systems represent a functional evolution in how payment networks manage ongoing vendor obligations through coordinated digital and institutional channels.