Biometric Synchronization Methods Matching Merchant Records to Global Wallet Movements in Subscription Credit Cycles
Petra Klein · Aug 23, 2026
Biometric Synchronization Methods Matching Merchant Records to Global Wallet Movements in Subscription Credit Cycles
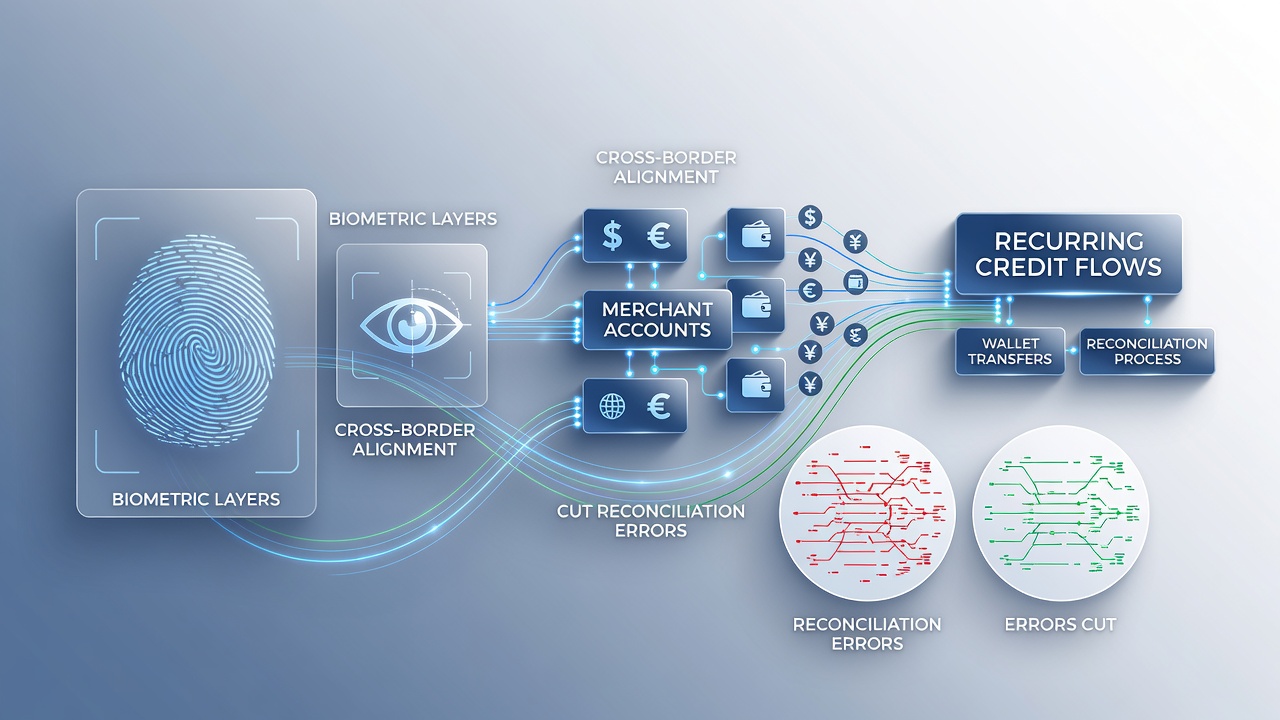
Biometric synchronization connects layered identity checks directly to merchant account ledgers and international wallet systems, which reduces mismatches during recurring credit movements across borders. Data from transaction networks shows that these alignments cut reconciliation discrepancies by matching fingerprint, facial, or iris patterns to each authorization step in subscription flows. Observers note that the process starts when a user initiates a recurring payment, at which point the biometric layer captures unique traits and links them to both the merchant record and the receiving wallet in real time.
Core Components of the Alignment Process
Merchant accounts store transaction histories while cross-border wallets handle multi-currency settlements, and biometric layers serve as the bridge that verifies identity at each transfer point. Research indicates that when a fingerprint scan or facial recognition occurs during authorization, the system timestamps the data and matches it against stored profiles in both the merchant database and the wallet provider's ledger. This matching happens before funds move, which prevents later disputes over who authorized the credit flow. Those who've examined payment infrastructures observe that the approach works across jurisdictions because biometric templates convert into standardized codes that comply with varying data protection rules.
August 2026 marks the scheduled rollout of updated interoperability standards from several central banks, including the European Central Bank and the Reserve Bank of Australia, that require biometric confirmation for all recurring cross-border transfers above certain thresholds. These standards build on existing protocols and aim to enforce consistent data fields between merchant systems and wallet platforms. Figures from pilot programs reveal fewer errors once the biometric match occurs at the point of authorization rather than during post-settlement review.
Reducing Errors in Recurring Credit Flows
Reconciliation errors typically arise when currency conversions, timing differences, or identity mismatches create gaps between what a merchant expects and what a wallet actually transfers. Biometric layers address this by embedding identity confirmation into every recurring cycle, so each credit pull carries verified user data that both sides can reference. A study conducted by researchers at the National University of Singapore found that systems using this method reported a measurable drop in manual adjustments needed after each billing period. The alignment occurs through API connections that push biometric confirmation codes alongside the payment instructions, allowing automated checks to flag any deviation before it reaches the reconciliation stage.
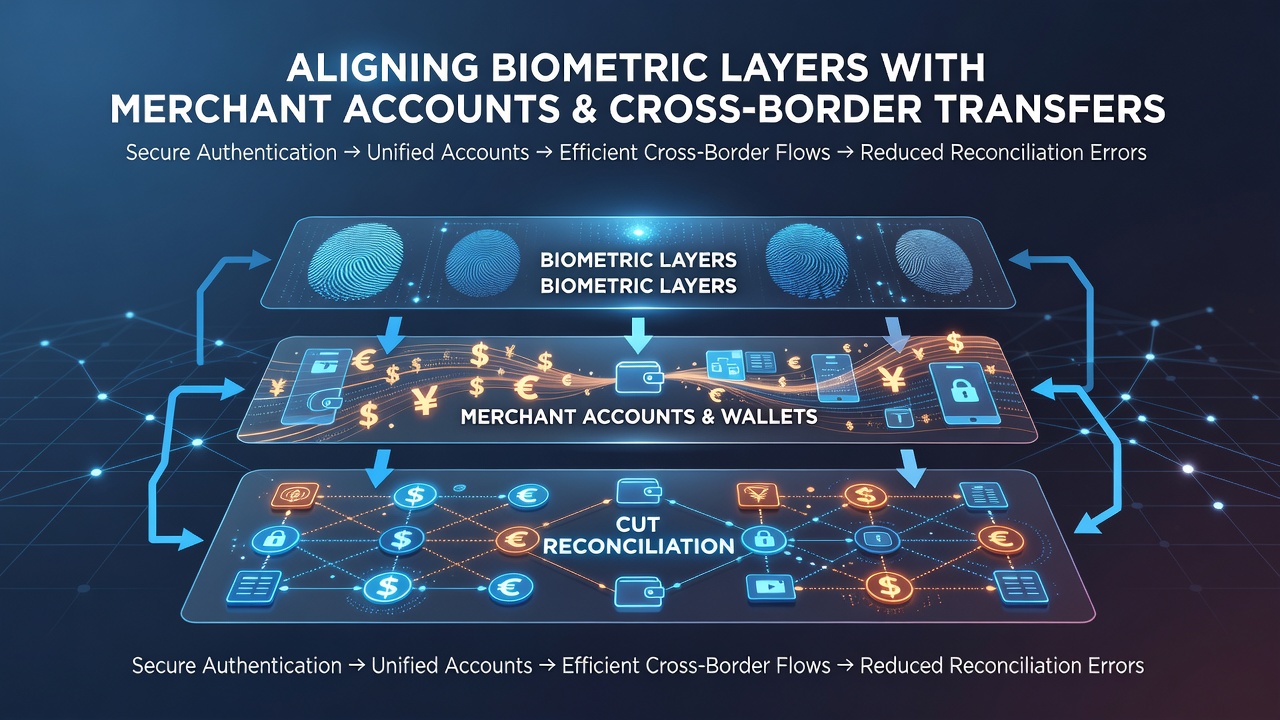
Take one merchant operating subscription services across Europe and Asia who integrated biometric checks at the wallet interface level. The company observed that disputes over failed recurring charges fell because each transfer included a matching biometric token that both the merchant account and the wallet provider could validate independently. This setup also supports high-volume cycles where multiple currencies move simultaneously, since the biometric layer remains consistent regardless of exchange rates applied at settlement time.
Technical Integration Across Networks
Integration relies on secure channels that transmit biometric templates without exposing raw personal data, using encryption standards already common in financial messaging systems. According to reports from the Bank of Canada, such channels allow merchant platforms to query wallet providers for confirmation matches before releasing recurring credits. The process uses hash functions to compare biometric codes, which keeps processing times low even during peak subscription renewal windows. Those who've mapped these sequences note that the verification occurs in milliseconds, fitting naturally into existing authorization flows without adding noticeable delays for end users.
What's significant is how the system handles exceptions, such as when a biometric scan fails to match. In those cases the transaction routes to secondary verification methods while still logging the attempt against both the merchant record and the wallet entry, which maintains an audit trail for later reconciliation. This approach ensures that even failed attempts contribute to accurate records rather than creating unexplained gaps.
Current Developments and Broader Applications
Industry data from 2025 shows increasing adoption among vendors managing international subscriptions, with biometric alignment appearing in platforms that connect directly to institutional banking channels. The reality is that regulatory updates expected in August 2026 will likely expand requirements for these layers in additional regions, pushing more merchants to adopt the synchronization methods. External analyses, including one from the European Central Bank, highlight how consistent biometric matching supports smoother operations when multiple currencies and time zones intersect in recurring credit movements.
Another source, a working paper from the University of Melbourne's payments research group, examines how biometric verification reduces settlement friction in wallet-to-merchant pipelines. The findings point to fewer discrepancies when identity data travels alongside each transaction rather than being checked separately after the fact. Observers tracking these trends see the pattern continuing as more platforms standardize the biometric fields used in cross-border communications.
Conclusion
Biometric layers that align merchant accounts with cross-border wallet transfers provide a structured method for lowering reconciliation errors in recurring credit flows. The process embeds identity verification into authorization sequences, which creates matching records on both sides of each transaction. Data from multiple regulatory and academic sources shows measurable improvements in accuracy once these alignments become standard. As updates take effect around August 2026, the same techniques are expected to extend across more markets while maintaining the same focus on consistent data matching between merchant ledgers and international wallet systems.