Integration Dynamics Between Mobile Interfaces and Institutional Systems for International Recurring Billing Security
Petra Klein · Aug 25, 2026
Integration Dynamics Between Mobile Interfaces and Institutional Systems for International Recurring Billing Security
Merchants operating across borders encounter recurring billing requirements that demand coordination between mobile interfaces and established institutional transfer channels, and this coordination produces observable patterns in authorization flows and settlement reliability. Data from multiple jurisdictions shows that mobile applications now handle initiation steps while routing verification requests through banking networks that maintain compliance with regional standards. Researchers tracking these interactions note that synchronization occurs at several points including token exchange, currency conversion protocols, and status reporting mechanisms.
Mobile Interface Capabilities in Recurring Transaction Initiation
Portable device applications present users with subscription management screens that collect payment credentials once and store them through encrypted tokens rather than repeated data entry, while backend processes route those tokens to institutional endpoints for authorization. Studies conducted by the European Central Bank indicate that interface designs incorporating one-tap confirmation reduce session abandonment during setup phases for cross-border plans. Observers note that developers incorporate fallback options such as stored bank details when card networks experience temporary latency, and this dual-path approach maintains continuity for merchants whose customer bases span multiple time zones.
August 2026 brought updated guidelines from the Reserve Bank of Australia that clarified token lifecycle management for recurring overseas charges, and those guidelines prompted several platform providers to adjust their mobile flows accordingly. Companies that implemented the changes reported fewer interruptions during monthly billing cycles, according to aggregated industry reports released later that year. Patterns emerge when interfaces detect location-based restrictions and automatically adjust the sequence of prompts presented to the user.
Institutional Transfer Channels and Their Role in Settlement
Banking networks receive authorization requests from mobile platforms adn perform checks against account balances, fraud indicators, and regulatory flags before releasing funds into merchant accounts, and these steps occur in sequence rather than in isolation. Federal Reserve data on cross-border volumes reveals that institutional channels process a rising share of subscription payments that originate on mobile devices, with settlement times averaging under four hours when both endpoints use standardized messaging formats. Those who monitor transaction logs observe that mismatches in currency conversion rates trigger secondary verification steps that extend processing windows but improve accuracy.
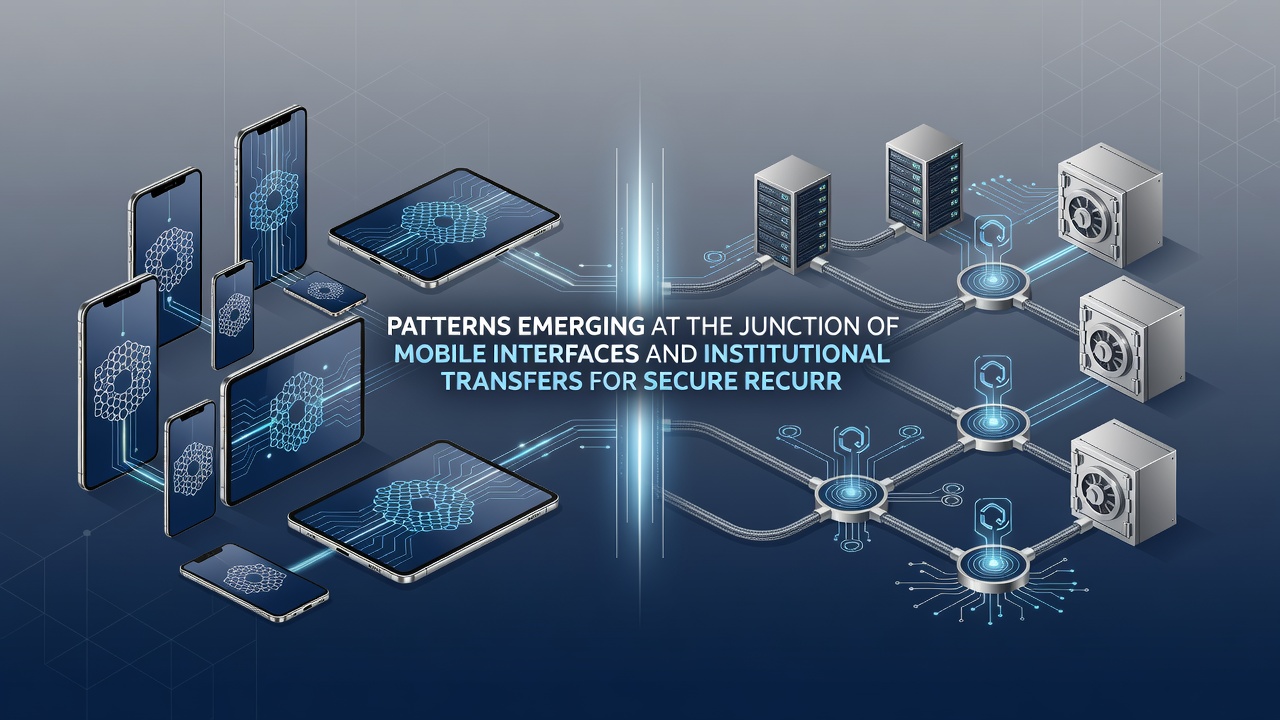
Integration points include API endpoints that mobile applications call to initiate transfers and webhook listeners that institutional systems use to push status updates back to the originating device. Patterns documented in technical papers from academic research groups show that latency spikes often coincide with peak subscription renewal dates, prompting providers to implement queueing mechanisms that prioritize high-value or high-frequency accounts. Merchants who align their mobile interfaces with these institutional timing requirements experience fewer failed collections.
Security Patterns Across Jurisdictions
Encryption standards applied at the mobile layer combine with institutional authentication layers to create layered defenses, and researchers tracking breach reports find that combined approaches correlate with lower rates of unauthorized recurring charges. Regulatory updates scheduled for release in late 2026 from Canadian authorities emphasize consistent logging of each transfer request, and this logging requirement affects how mobile platforms format their outbound messages. Observers note that merchants adopting these logging practices encounter smoother audits when expanding into new markets.
Token rotation schedules differ between card networks and bank transfer systems, yet mobile interfaces that accommodate both schedules reduce the frequency of re-authentication requests sent to customers. Data matching protocols that compare device identifiers against known account histories add another verification dimension, and patterns indicate that successful matches shorten overall authorization times. Those managing large subscription portfolios report that these combined security elements support higher retention rates when customers reside outside the merchant's primary operating region.
Observed Coordination Examples
One documented case involved a software provider that adjusted its mobile billing screen to query institutional availability before displaying renewal amounts, and the adjustment resulted in fewer declined transactions during periods of currency fluctuation. Another instance showed that platforms incorporating regional compliance checks at the interface level experienced faster settlement when routing payments through multiple banking partners. These examples illustrate recurring coordination points rather than isolated successes.
Conclusion
Patterns continue to form at the points where mobile interfaces meet institutional transfer systems, and ongoing regulatory developments scheduled through 2026 and beyond will likely refine those interaction sequences further. Merchants and platform developers who track authorization success rates, settlement timing, and compliance logging requirements maintain visibility into the evolving structure of secure recurring billing for overseas commerce.