Niche Retailers Align App Ecosystems with Banking Channels for Efficient Multi-Currency Recurring Authorizations
Petra Klein · Sep 5, 2026
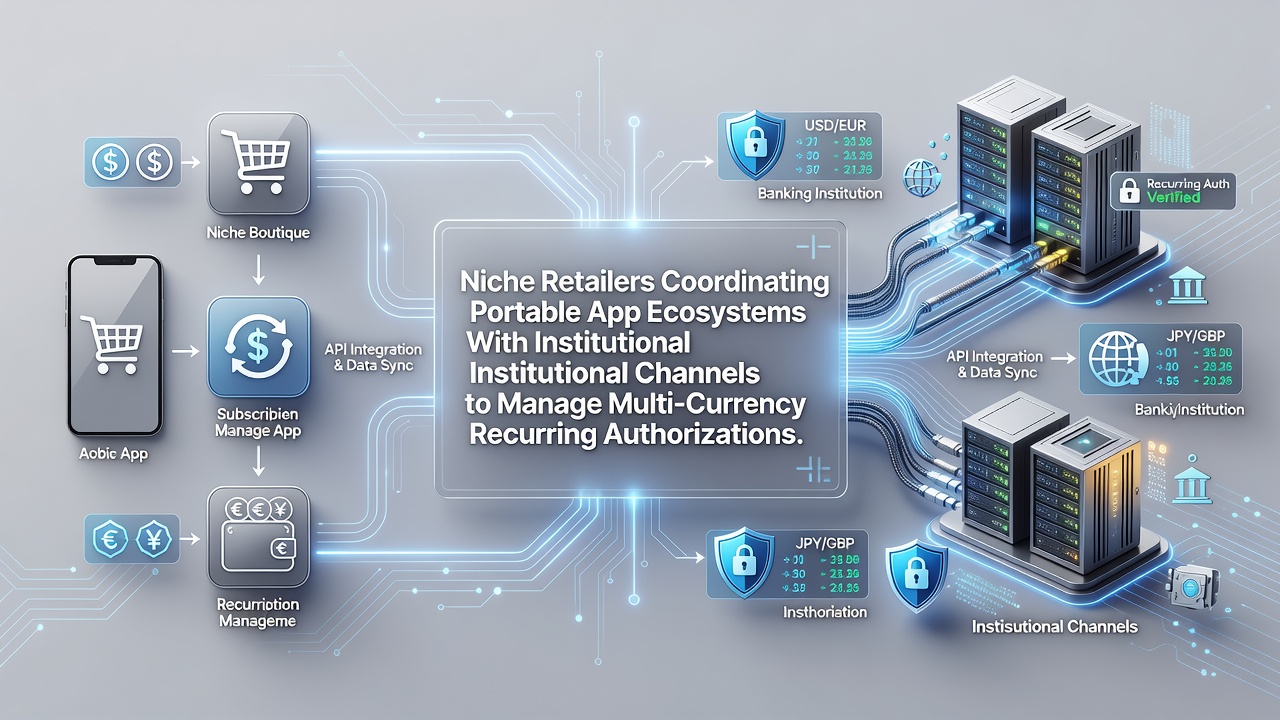
Niche Retailers Align App Ecosystems with Banking Channels for Efficient Multi-Currency Recurring Authorizations
Specialty merchants in sectors such as health supplements, hobby equipment, and subscription-based education services have developed methods to connect portable application frameworks with established banking institutions, allowing them to handle recurring payments that span multiple currencies without disruption. These approaches rely on synchronized data exchanges between mobile platforms and core banking systems, which process authorizations while converting amounts according to real-time exchange rates. Observers note that such coordination has become essential as niche retailers expand into overseas markets where customers prefer local currencies for ongoing charges.
Core Integration Mechanisms
Retailers establish application programming interfaces that link their portable apps directly to institutional payment processors, enabling automated verification of recurring authorizations across different currency zones. Data flows through encrypted channels that update transaction ledgers in both the mobile environment and the bank's settlement systems, reducing the chance of mismatched records during monthly or quarterly billing cycles. Research from the Bank for International Settlements indicates that these linked systems handled over 12 billion multi-currency transactions in 2025, with niche operators contributing a growing share.
Security protocols require each authorization request to pass through layered checks, including token generation on the device side and confirmation against the institutional account balance on the banking side. When a customer in one region subscribes using euros while the retailer settles in dollars, the system triggers an immediate conversion step followed by a second authorization to lock in the rate for the full subscription term.
Handling Currency Fluctuations
Fluctuations in exchange rates create ongoing challenges for recurring charges, yet coordinated platforms address this through scheduled rate locks and fallback procedures. When volatility exceeds preset thresholds, the mobile app notifies the institutional channel, which then applies adjusted authorization amounts while preserving the original subscription terms. Data from the European Central Bank shows that coordinated systems reduced failed recurring payments by 18 percent in markets using more than three currencies during the first half of 2026.
Operational Examples Across Regions
One health-product retailer operating in North America and Southeast Asia routes all subscription renewals through a unified mobile dashboard that communicates with both regional banks and global card networks. The institutional side processes the currency conversion and returns a single settlement file, which the app then reconciles against customer records. Similar patterns appear among hobby-equipment vendors that expanded into European markets after 2024, where they adopted standardized messaging formats to ensure portable authorizations align with local banking settlement windows.
Retailers in these setups also maintain audit trails that span both ecosystems, allowing compliance teams to trace each authorization from the initial mobile trigger through to final institutional posting. This traceability supports regulatory reporting requirements in multiple jurisdictions without duplicating data entry.
September 2026 Developments
As of September 2026, several industry groups released updated technical specifications that standardize how portable apps exchange recurring authorization tokens with institutional channels. These specifications emphasize compatibility across currencies and include provisions for instant settlement options when both systems support faster payment rails. Merchants adopting the new formats report shorter reconciliation periods, often completing monthly reviews within two business days instead of the previous five.
Conclusion
Niche retailers continue to refine the connections between their portable application ecosystems and institutional banking channels to sustain reliable multi-currency recurring authorizations. The resulting frameworks support growth into new markets while maintaining accurate settlement across currency boundaries, and further refinements are expected as technical standards evolve.